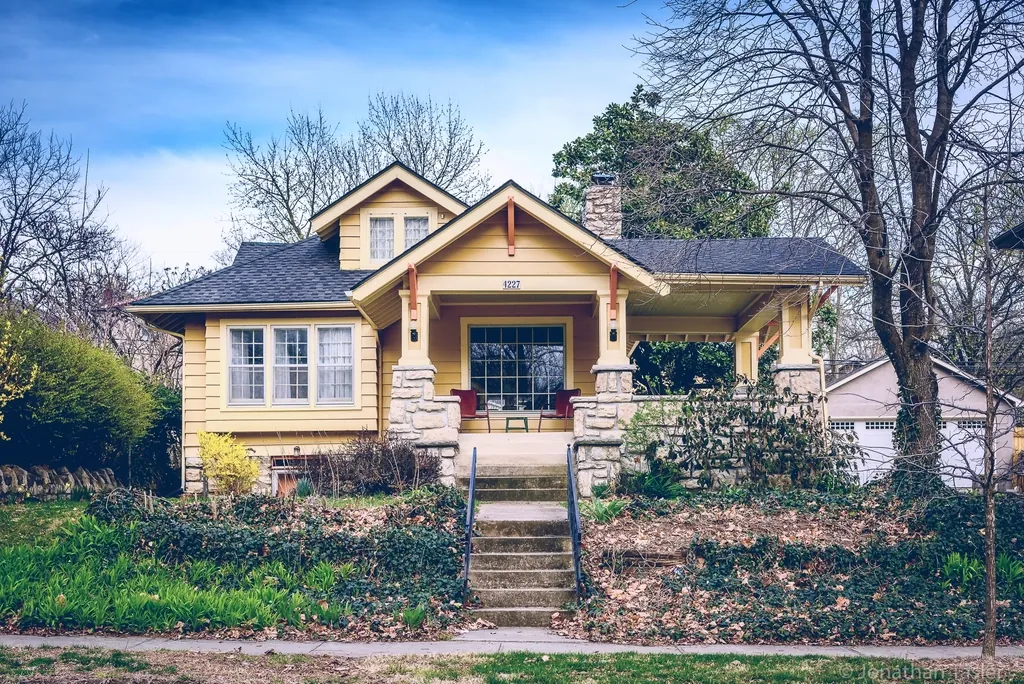
Why home claims come up short
Most residential underpayments are not dramatic denials. They are missing pieces: one slope left off the roof scope, gutters and downspouts ignored, a window wrap that was never priced, or a detached garage nobody inspected. Each item is small. Together they can be the difference between a finished repair and a second mortgage.
Nebraska homes add their own complications. Many older houses in Lincoln, Omaha and Hastings have layered roofs, wood lap siding under vinyl, plaster walls and original trim that standard line items do not price well. Newer subdivisions in Papillion, Gretna and northwest Lincoln often have complex roof lines with valleys, dormers and steep pitches that change both labor and waste.
What a residential appraisal file covers
- Roof, gutters, soft metals, vents, skylights and satellite mounts
- Siding, window wraps, screens and paint on every elevation
- Detached garages, sheds, fences and acreage outbuildings under Coverage B
- Interior water damage, insulation and drywall after roof or pipe leaks
- Contents and additional living expense questions where the policy allows
Acreages and rural homes
Acreage policies often split the home, other structures and farm property in ways that matter at claim time. A machine shed may sit under the homeowners form, a farm schedule or a separate policy entirely. We read the declarations first so each building is valued under the coverage that actually applies.
Working alongside your contractor
Your contractor knows the repair. We know how an appraisal panel reads an estimate. We often meet contractors on site, review their numbers and make sure the work they plan to do is reflected in a defensible valuation.
Questions about this service
Do you handle claims on rental houses?
Yes. Landlord and dwelling-fire policies have their own valuation terms, often actual cash value instead of replacement cost. We value the loss under whatever form is in force.
Is my detached garage covered the same way as my house?
Usually it falls under Other Structures (Coverage B) with its own limit. The valuation method is often the same as the dwelling, but the limit can be much lower.
My adjuster only inspected from the ground. Is that a problem?
Ground-only inspections often miss slope-by-slope hail damage, soft metal hits and steep-pitch details. A full roof inspection is one of the first things we do.